Open the visual model ↗
The deliberately small model
This is an illustrative month, not a publisher case or a rate recommendation. Assume a specialist newsletter delivers 2,400 emails each week and has four issues. It sells one clearly labeled fixed sponsor slot in every issue for $300, plus an affiliate placement in two issues. The audience, geography, price, and every conversion assumption are invented.
The sponsor produces $1,200 in gross revenue: four placements times $300. For the affiliate placement, assume 80 qualified clicks in each of two issues, a 3.0% validated purchase rate, a $90 eligible net sale, and an 8% commission. That produces 4.8 expected validated purchases and $34.56 of gross commission. Expected-value arithmetic is useful for planning, but it is not an observed fractional order count.
What the month contributes
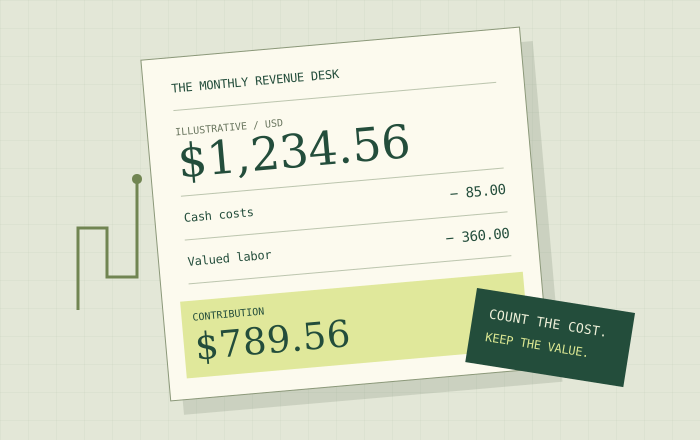
Gross revenue is therefore $1,234.56. Subtract $60 of incremental newsletter-platform cost, $25 of creative or tool cost, and eight sponsor-sales and fulfilment hours valued at $45 each. The illustrative contribution is $789.56, or 63.95% of gross revenue. This is contribution after the named incremental costs, not accounting profit, tax advice, or a cash forecast.
The apparent strength has a simple cause: the fixed sponsor supplies 97.2% of modeled gross revenue. The affiliate line is small and depends on a handful of purchases. That makes the model sensitive to one sponsor leaving, a late payment, a missed placement, or extra work that was not budgeted.
- Sponsor gross: 4 × $300 = $1,200.00.
- Affiliate gross: 2 × 80 × 3.0% × $90 × 8% = $34.56.
- Named cash costs: $85.00; valued labor: $360.00.
What to observe before repeating it
A publisher should record delivery, sponsor renewal, payment collection, clicks, unsubscribes, complaints, and the actual hours required. The booking should also state what is counted, who owns the count, exclusions, and the remedy for an underdelivery. A direct placement is a contract and a relationship, not a line in a dashboard.
Open counts are intentionally absent from this arithmetic. Apple says Mail Privacy Protection can download remote content in the background regardless of engagement, so an open is not a clean measure of a person reading. Sponsors can still receive a useful report, but its limits should be part of the report.
Sources & limits
All revenue, cost, volume, and conversion figures are illustrative assumptions; the example does not predict sponsor demand, list quality, or earnings.
- Mail Privacy Protection & Privacy
Platform documentation · Publication date not stated · Referenced in the earlier research pass · 15 September 2026 - When will I receive payment?
Affiliate-network documentation · Source published 19 June 2020 · Referenced in the earlier research pass · 15 September 2026
Source claims and editorial judgments remain separate. Send a correction with the passage and supporting evidence.